- Finance/Geopolitics
- Global Chaos
- Investment Powerplay
- Macro/CountrySpecific
- Open Door Category
- Weekly Weigh In
- Writer's Journal
Company
Soma Gold Corp. (TSXV: SOMA) is a profitable, Vancouver-based junior gold mining company focused on the acquisition, exploration, development, and production of gold assets in Colombia’s Antioquia Department.
Let’s start with the bad news
- Financial results have deteriorated sharply. YTD 2026 net loss was C$6.0M versus C$4.8M net income a year earlier. For a relatively small mining company this is . Adjusted EBITDA fell from C$22.3M to C$6.8M, and Q2 gross margin of this year dropped from 25% to an unexciting 10%. This was the result of a massive 65% reduction in cash margin on every ounce on gold sold.
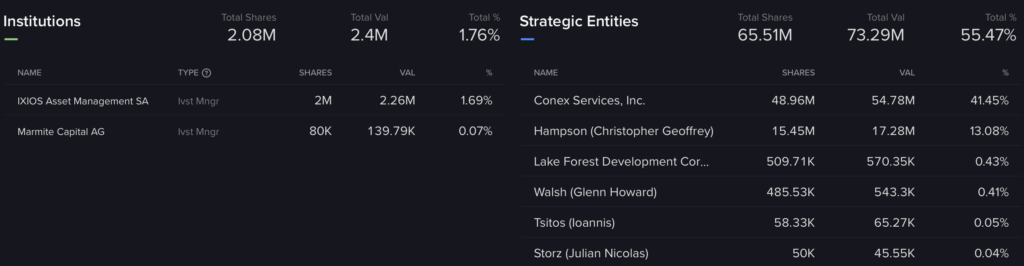
- A debt swap and placement had recently added a lot of shares. The stock has been weak, with a C$0.91 close in late May and C$0.68 by July 23, below the C$0.75 placement price. This had upset some investors for obvious reasons. Soma issued 33,436,442 new shares across the two deals
- Execution and operating risk in Colombia. A labor strike shut operations from September 9 to November 5, 2025. This lead to a mill throughput in H1 2026 4% below the prior year. The company also has a history of grade surprises at Cordero, which isn’t inherently destructive, but the market doesn’t like how it looks for a single project producer.
Assets
Processing plants
- El Bagre Mill (El Bagre Gold Complex): the main operating plant, running at around 450 TPD. New ore sorting equipment is being set up there.
- El Limón Mill (Zaragoza): restarted in Q3 2025 to handle more volume from company mines like Aurora and Escondida and from third-party formalized miners
Mines and projects
- Cordero Mine: the flagship. Operations stabilized after last year’s labor disruption, with production back to 425–450 TPD.
- Aurora Mine: Purchased in 2024. Colombia’s ANM approved an increase from 25 to 75 TPD in July 2026.
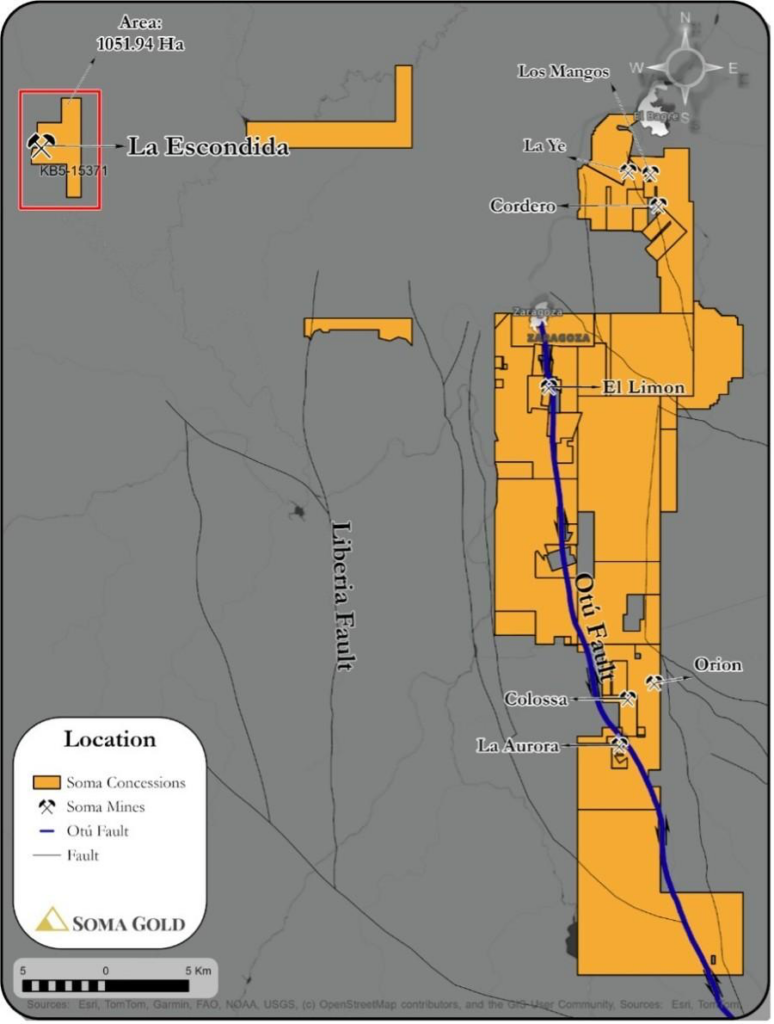
- Escondida Mine: Acquisition closed in December 2025. Production started at 10 TPD, with 40 TPD permitted capacity targeted for Q1 2027.
- El Limón Mine: Operated from 1995 until closing in 2020 due to low gold prices, then flooded. It has since restarted. In September 2025 Soma signed a binding agreement to buy back the El Limón NSR royalty from Red Rock Resources.
- Nechí Mine/Project: Includes the El Catorce, Santa Elena and Santa Maria exploration projects. Once built, it’s expected to add about 250 TPD of feed to the El Bagre Mill, or roughly 25,000 AuEq ounces a year.
- Diamantina Mine: a formalized small mine on Soma’s ground. Soma buys its ore in return for a portion of the gold in each delivery. It is the first of 24 small mines in formalization, out of about 60 small operations on the property.
- La Ye and Los Mangos: older underground mines that came with the El Bagre operation, along with the Cordero project.
- Zara exploration properties: About 29,000 hectares in Antioquia, now part of the overall concession package.
Brazil (Exploration)
- An exploration property near Tucumã, Pará state in Brazil, under option to Ero Copper Corp.
It owns two adjacent mining properties in Antioquia, Colombia, with combined milling capacity of 675 tonnes per day (permitted for 1,400 TPD), and the El Bagre Mill is currently operating. Its main source of ore is the Cordero underground mine, with smaller mines (Aurora, Escondida, El Limón) being brought on air.
On the El Bagre Gold District they it control over 43,000 hectares of mineral concessions along the prolific OTU fault with the Cordero Mine.
Processing Mill
Additionally, their edge comes out of having two fully permitted Merrill Crowe processing mills — with a combined expandable capacity of up to 1,400 TPD (targeted capacity).
They have acquired a producing gold mine in Colombia in 2017–and made six other acquisitions since then–most of which are in recent years that the market has not appreciated.
Mining Story
Development of the Cordero mine began in September of 2020 and commercial production was achieved as of January 1, 2023. Soma’s legacy mines, La Ye and Los Mangos, have been mined out and were decommissioned in early 2023. This had put Soma on the back burner of interest for investors since their flame seemingly had run out. However, going forward, Cordero has already been feeding their mill and the numbers are only increasing from here.
The Cordero Mine is expected to increase mine production and feed the El Bagre Mill with two ore sources: (i) direct high-grade material from the Cordero Mine, and (ii) grade-enriched Cordero material from ore sorting equipment. This strategy is expected to sustainably support high-grade gold production at the El Bagre Gold Mining complex.
Ongoing drill programs have constantly replenished resources at the Cordero Mine.
MRE Too Small?
- Cordero Deposit (El Bagre Complex):
- Indicated: 355,000 tonnes @ 6.90 g/t Au (78,000 oz)
- Inferred: Higher grade resource footprint (averaging ~7.9 g/t Au)
- Nechí Project:
- Indicated: 310,000 tonnes @ 4.90 g/t Au (49,000 oz)
The MRE isn’t too impressive on first glance but some factors stand out.
The grade of gold they are mining allows them to get away with fewer ounces and also this was published in Dec 2022–so it doesn’t include any of their newer acquisitions, expansion drill programs or other concessions. Even this small MRE provides a 1.5–1.7x P/NAV
Gold mineralization in the quartz-carbonate veins is associated with pyrite, galena, sphalerite and tellurides, and locally free gold.
While it’s true that cash margins have fallen, of now US$969/oz in Q2 versus US$1,598/oz a year earlier–gold prices have since increased and we’re still getting about 1000 dollars per ounce mined for profit.
Q1/Q2 2026/Income
- Revenue for the first quarter of 2026 was $22.5 million – a decrease of 19% from 2025-Q1.
- Net loss for the first quarter was $2.1 million, compared to a net income of $3.2 million in 2025-Q1
Q2 2026
- Revenue for Q2 2026 decreased to $20.4 million (Q2 2025 – $23.0 million), representing a $2.6 million or 11% decrease. Revenue for YTD 2026 decreased to $42.9 million (YTD 2025 – $50.9 million), representing an $8.0 million or 16% decrease.
- Income from Mine Operations decreased by $3.7 million to $2.0 million in Q2 2026 (Q2 2025 – $5.7 million) while gross margin decreased from 25% in Q2 2025 to 10% in Q2 2026. The Company produced and sold fewer gold equivalent ounces and incurred higher production costs. The reduction in sales volume was partially offset by a higher average realized gold price.
- Net loss for Q2 2026 was $3.9 million compared to net income of $1.6 million in Q2 2025. Net loss for YTD 2026 was $6.0 million compared to net income of $4.8 million in YTD 2025.
Q1 2025
- Q1 2025 revenue: $27.9M, up 44% from last year (2024)
- Net income: $3.17M, flipping from a loss a year ago
- Adjusted EBITDA: $13.47M — enough to cover the full raise in just over a quarter
- Cash costs: US$1,261/oz vs selling price of US$2,903/oz — fat margins (although these are even higher now)
- Debt reduction: $3.5M since January, targeting zero by 2028
- P/E ratio: 18.93
Working capital fell to C$12.9M at June 30 from C$17.2M at year-end, with C$7.2M in cash and short-term investments.
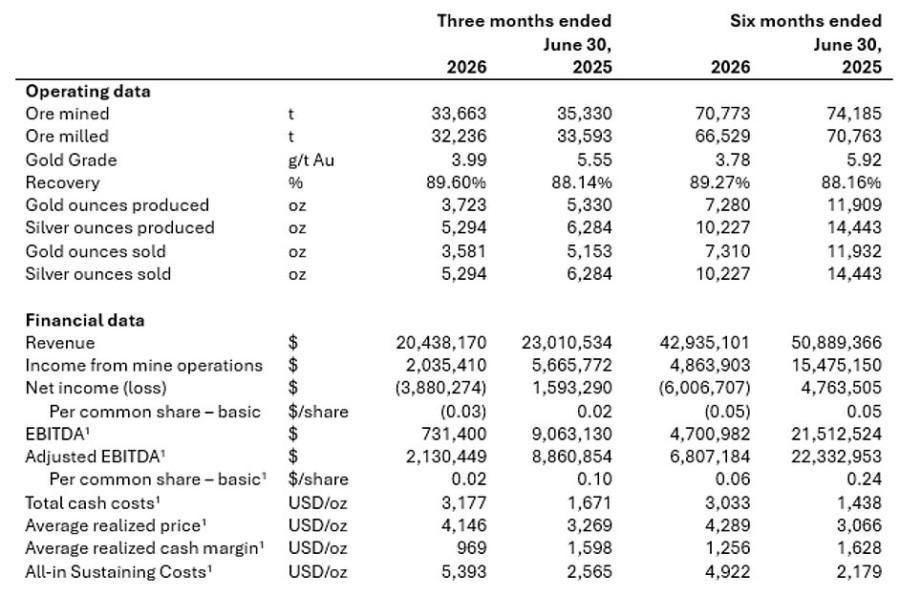
These numbers are a result of capital expenditures and changes of underlying gold prices, as usual.
Do you want to invest in companies like this with enormous upside? Contact Partners@sealionoffice.com with a simple email
62K ounces?
With their new processing technology, for only about $1.5M they’re aiming to more than double the capacity of their mill. Now, the CEO (Geoff Hampson) has a target of 5200 gold ounces per month in 18 months from now. That’s 62k per year. Relative to where they are trading this is a nice jump in valuation: If Soma Gold successfully produces 62,000 ounces per year, its revenue depends directly on the market spot price of gold:
At a hypothetical gold price of $2,600/oz, annual revenue would be roughly $161.2 million. That’s only a P/E of 0.57
The El Limon mill restart brings in ore from the Aurora patch, and Cordero excess, and higher-grade local artisanal supply. Management has indicated that Cordero grades are expected to improve meaningfully in the second half of 2026 as higher-grade areas and additional mine feed are incorporated into the production play
Expansion
As a producer, they’re pumping around 2,000 ounces per month but they’re currently in expansion mode. They’re able to expand this from their new ore equipment and a new mine coming on air.
Their latest capital raise is not for survival or for security moving forward–it’s to expand their throughput.
- $10m of the financing is converting existing debt into equity, taking that overhang off the books immediately (though smashing the share price as you’ll see below).
- Exploration is fully funded from free cash flow with 30,000m drilling annually, five rigs running, and new vein discoveries already making an impact. In other words, despite previous dilutions, they’ve de-risked this aspect for shareholders.
- The company has a district-scale land package along the Otú Fault to grow into, right beside Aris Mining’s Segovia operation (an operation that produces +230,000 ounces of gold annually). The company expects to receive environmental and mining approval before the end of 2026. Once approved, the Nechí project is slated to act as the next major growth leg for the company, supplying an additional 250 tonnes per day of feed to the El Bagre Mill and yielding an extra 25,000 ounces of gold per year.
- Upgraded ore sorting tests could push production to 65-75k oz/year, with potential to 85-100k oz/year after a modest mill expansion
The $7.5 million private placement is set to accelerate production growth at both the Escondida and Aurora mines, with ore sorting infrastructure nearing completion
Points
Producers with cash flow, expansion potential, and exploration upside are rare. Soma stands out because:
- High-gold-price market–leading to exponentially higher margins.
- Potential for growth in both mining and processing
- Operates in a pro-mining jurisdiction with government support for its artisanal miner formalization model
- Soma is a strange set up of having numerous small mining operations with increasing scalability to process tonnage. Each mining project by itself is not compelling but together it calls for dramatic upside.
Worth Mentioning
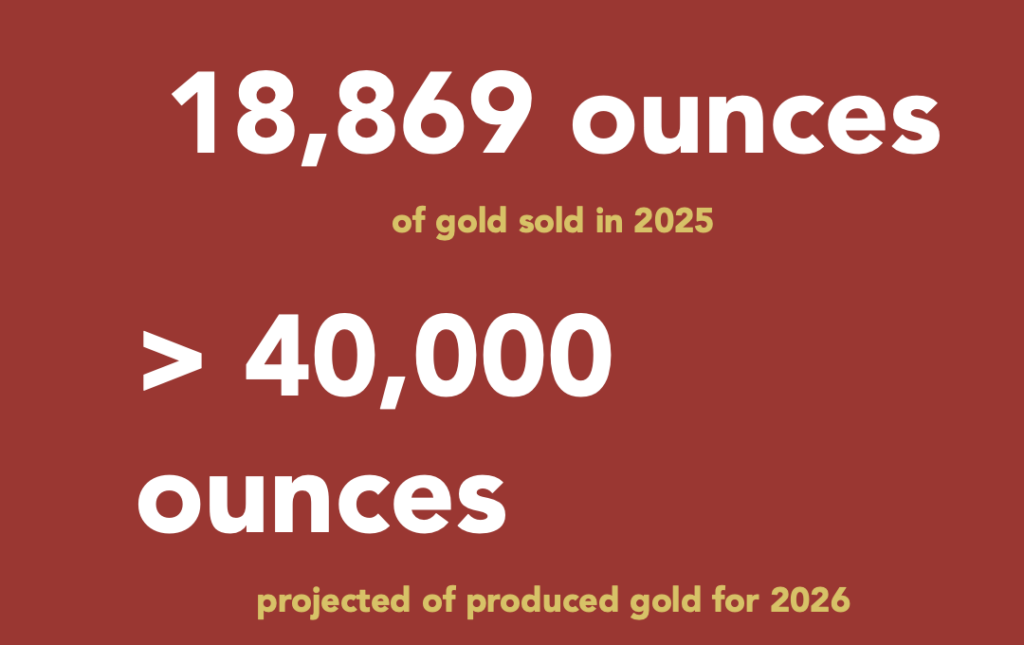
Soma’s own CEO acknowledged the company is several months behind its production increase schedule, with 2025 AuEq output of only 18,670 ounces falling short of expectations due to a prolonged strike, hiring difficulties, and mechanical issues. These repeated operational setbacks cast doubt on management’s ability to execute its ambitious ramp-up timeline
The Valuation Gap
Compared to Colombian peers, Soma is trading at a fraction of the EV/EBITDA multiple — despite being profitable, debt-reducing, and on track for big production growth. It’s worth also reiterating the high-grade material they have in South America compared to peers.
This gap isn’t because the market doesn’t know they’re profitable; it’s because the production growth story hasn’t fully registered. That could change quickly as the second mill comes online, ore sorting boosts grades, and more high-grade feed gets blended into the mix.
- EV/EBITDA around 3–3.8×, significantly lower than typical peers in gold mining, which often trade in the 8–12× range or more. This ranges is considered conservative, especially given Soma’s growth prospects.
- Price-to-Earnings (P/E) sits around 16×, while peers and broader mining industry averages sit much higher—often in the 50–60× range.
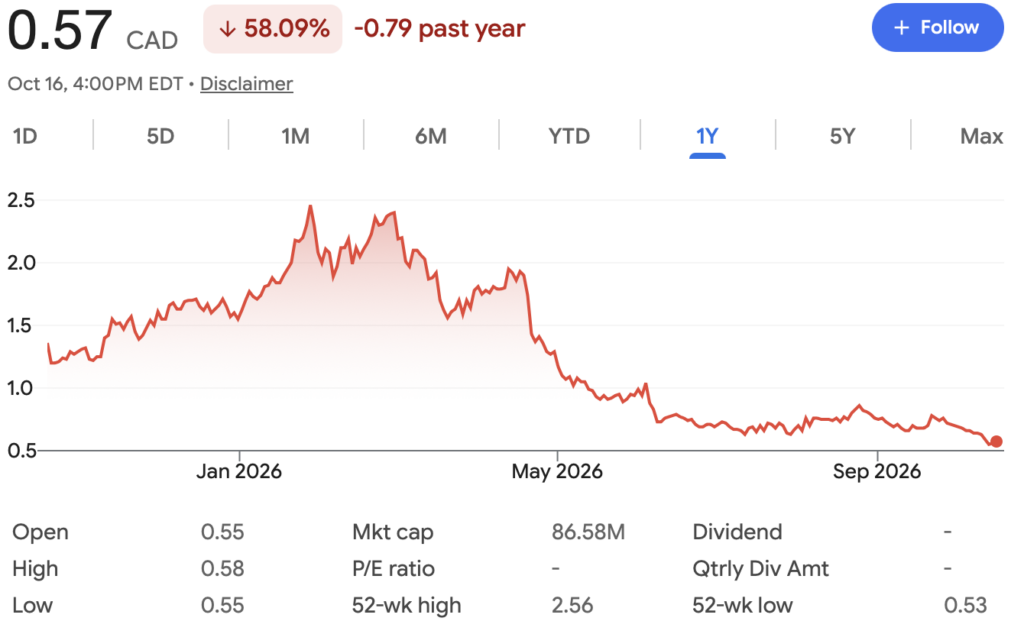
- Multiple fair-value models suggest Soma is deeply undervalued. One DCF-based forecast by Simply Wall St pegs fair value at around C$7 versus the current ~C$0.57 share price—a gap of ~90–92% undervaluation
Ownership
Latest News
- Oct. 16, 2026 /CNW/ Soma Gold Corp. has arranged an unsecured revolving credit facility of up to C$2,500,000 from Hampson Equities Ltd. (the “Lender”), a company controlled by Geoff Hampson, CEO and Chairman of the Company. Soma intends to use the proceeds from the Credit Facility for working capital purposes and to support the purchase of mineralized material from third-party producers in Colombia
- September 2026: Shows the results of surface drilling at the Cordero Mine in Antioquia, Colombia. Sixteen drill holes have been completed at Atenas, totalling 1,838 m in 2026
- Soma is pleased to announce a non-brokered private placement offering of up to 10,000,000 common shares of the Company at a price of C$0.75 per Share for aggregate gross proceeds of up to C$7,500,000 (June 9th)
- Escondida Mine to the El Bagre Gold Complex have commenced (June 8th)
- Soma is pleased to announce that it has agreed to settle $25,780,086 of debt through the issuance of common shares of the Company. Pursuant to the debt settlement, the Company will issue 23,436,442 Shares at a deemed price of $1.10 per Share to Conex Services Inc., a company owned and controlled by Glenn Walsh, a director of the Company. The Debt was originally incurred in connection with a previous debt restructuring (June 2nd)
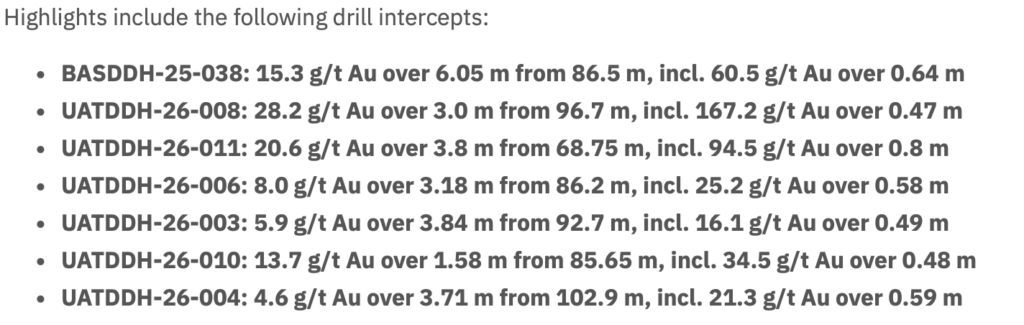
- Recent drill assays in Venus Gap and Psyche 2 are showing multiple intercepts of well over 20 g/t gold — grades that translate directly into stronger cash flow.
Tough 52 Weeks
Closing
Soma gold is an interesting company given its relatively modest market cap against its ability to produce without any debt obligations holding it back. It has disappointed as of late and investors have a bitter taste in their mouth; Higher costs, with three delays on the restart of their smaller mines (Escondida restarted only in June, after flood damage, Aurora was waiting on its explosives permit, the final permit needed to restart, which wasn’t granted until June 2026 and at Diamantina, industry-wide competition for labour slowed mobilization) coupled with a strike protest that derailed operations and a reduction of expected gold grade have all formed the perfect storm. Worse yet, a conversion of debt to equity had diluted shareholders.
Ultimately, Soma Gold is a turn-around story after it has gotten completely beaten up over the last 52 weeks.
With this said, the storm seems to be behind shareholders are looking at a company that is producing gold ounces being poured right now. More than simply producing ounces, they have a clear expansion plan with various properties and mill processing entering into the equation supported by access to a credit facility with no pending debts and continued high-grade finds. It’s worth reiterating that the neighborhood they’re in close to Aris Mining is extremely gold rich.
If we consider a scaling to processing 62,000 ounces a year, at a margin of 2,500 USD per ounce, we’re looking at a massive valuation differential between the current share price and their annual earnings.
Very few get near the development point that Soma is at right now, with their own mills (plural), with permits in hand, debt being lowered rather than expanded, and gold being poured. Soma gold is a play that their small properties will continue to feed into their own mill and especially with higher gold prices, create a massive mis-valuation opportunity for investors.