A Junior Mining Company: Assays or Nothing
Company
GoldHaven Resources (CSE: GOH))
is a Canadian junior metal exploration company. The Company is focused on acquiring and exploring highly prospective land packages in North and South America. The Company’s projects include the flagship Magno Project, a district-scale polymetallic property adjacent to the historic Cassiar mining district in British Columbia.
The Three Guardsman Project, which exhibits significant potential for copper and gold-skarn mineralization. The Copecal Gold Project, a drill-ready gold project located in Mato Grosso, Brazil with a six kilometer strike of anomalous gold in soil samples. Three Critical Mineral projects with extensive tenement packages totaling 123,900 hectares: Bahia South, Bahia North and Iguatu projects located in Brazil. Rio Loa is located 25 kilometers south of the Gold Fields Salares Norte project. T
Story
Goldhaven resources has only existed for about 6 years, starting out as a Chilean focused operation with little success. Then, in late 2024 and early 2025 it was rebuilt around new assets in British Columbia and Brazil and is now focused on its flagship project.
It explored the Maricunga Gold Belt of northern Chile and raised about $2.45M in late 2020, mostly to fund exploration there. Four of its seven Chilean properties were rated high priority–but the drill results left a lot to be desired.
After a turn around, they acquired a new set of assets (I will let you know how they bought these below).
- BC assets. GoldHaven bought Copper Peak Metals under an agreement signed October 31, 2024. That brought in the Magno and Three Guardsmen properties for 3.99M shares at a deemed $0.09 plus 1M warrants.
- Brazil assets. On January 13, 2025 it closed the acquisition of Boa Gold, gaining 100% of four Brazilian projects: Copeçal, Bahia North, Bahia South and Iguatu. GoldHaven’s broader portfolio includes the Copeçal Gold Project in Mato Grosso, Brazil, a drill-ready gold target with a 6-kilometre strike of anomalous gold in soil, and three critical mineral projects in Brazil totalling 123,900 hectares.
Flagship: Magno Polymetallic Project in the Cassiar region of northwestern British Columbia
Their flagship is now Magno, and specifically the historical deposit at Kuhn–Dead Goat.
Earlier operators outlined roughly 616,500 tonnes grading 0.48% WO₃ across four modelled lenses.
- Reported historical drill intercepts include 13.0 m at 0.55% WO₃ and 4.0 m at 1.32% WO₃ with 0.26% MoS₂.
- BC assessment records show Shell Canada drilled the Dead Goat skarn at some point (343.5 m). By 2016 the Kuhn claim was held by an individual prospector, William Pfaffenberger–where they acquired the property.
Three Guardsmen (northwest BC)
The project lies near Haines Junction. Its 2025 program took 126 surface samples, 25 of them above 1% copper, with grab samples up to 15.85% Cu. The company believes there may be a porphyry copper system at depth and started an IP survey in July 2026 to look for it. It has not been drilled yet.
What are they doing with the money raised?
GoldHaven recent capital raise is to fund 2026 exploration at Magno, this will be done using 3D geological modeling, drill target refinement, and permitting for an initial drill program designed to test the scale and vertical extent of the mineralizing system across several priority zones within the property.
The planned program will evaluate porphyry, carbonate replacement silver-lead-zinc, tungsten-skarn (perhaps the most interesting), and critical mineral targets identified through the company’s integrated interpretation of structural, geochemical, and geophysical datasets.
Thus far at Magno, they returned 357 samples revealing bonanza silver grades up to 2,370 grams per tonne and tungsten values reaching 6,550 ppm across multiple skarn zones. The company also confirmed high-grade copper at its Three Guardsmen Project, with surface sampling returning up to 15.85% copper (which is outrageously high-grade).
Upside Explosion Catalysts
While GoldHaven just started its maiden drill program and most assays are still remaining, It has already recently reported up to 55.3 g/t gold from Magno. If drilling demonstrates continuity/scale around those high-grade results through the most recent assays, the market could aggressively re-rate the share price.
What’s more is that if you’re of the opinion that we’re in a commodity bull-run, or that major deficits are coming in the next 10 years, you’d be pleased to hear that their projects contain more than just gold. They have found silver, copper, tungsten and indium (last two being a critical mineral on every government’s shopping list lately).
Wayne Gretzky famously said you miss all of the shots you don’t take–Goldhaven have multiple shots on goal with their six 100% owned projects. Copeçal in Brazil (moving into Phase 2 of its drilling program) and Magno/Three Guardsmen in BC as the main assets. Investors don’t necessarily need every project to work—one meaningful discovery could materially change the story for this company.
Shares Beaten Up Since They’re Switch of Focus
GoldHaven has faced several challenges that have affected its performance and investor confidence. In June 2024 (although before the switch), the company announced the termination of its options on the Smoke Mountain 1–4 and 5–7 claims, a key project in British Columbia (or so investors thought). Additionally, the broader downturn in the junior mining sector, combined with fluctuating gold prices has placed further pressure on its performance. The company also reported a debt settlement involving the issuance of shares to a creditor, resulting in further shareholder dilution.
The most recent news for us is that they’re actively doing diamond drilling at the Kuhn District.
Stock
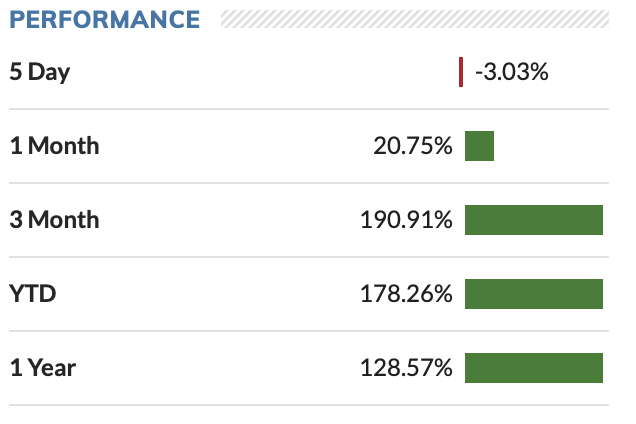
- 52 WEEK RANGE 0.09 – 0.39 (massive range)
- MARKET CAP$14.65M
- SHARES OUTSTANDING 87.4M (Massive dilution following the share split). In October 2024 there were about 5.56M
- PUBLIC FLOAT40.11M
Ownership
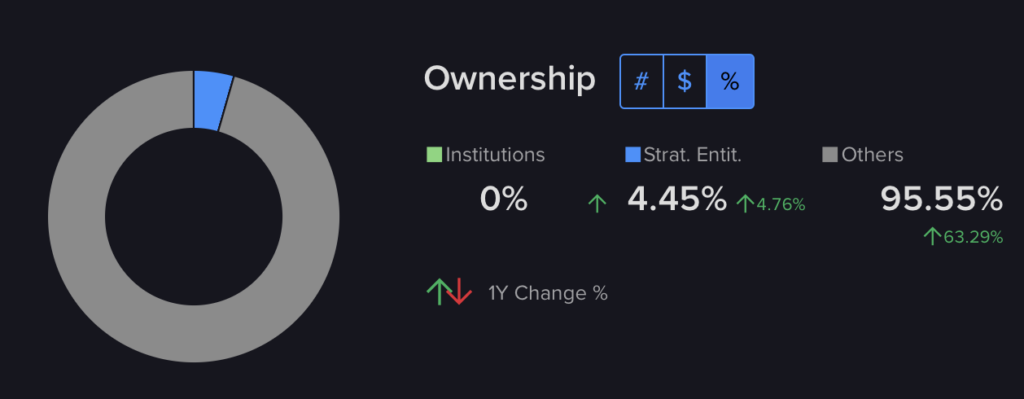
Virtually all retail ownership of the stock… does this paint a bad picture?
Things I like
- Drilling upside and exposure to Tungsten (be sure to see our article on this metal).
- Crazy high grade silver with consistency across new, unexplored property.
- Numerous exploration targets available
- Management changes taken places who appear aiming properly
- Stupid small market cap
- Surface results I’ve already mentioned: Grab samples returned up to 2,370 g/t silver, over 20% lead and 19.25% zinc, with 45 of 357 samples above 100 g/t silver. Indium reached 334 ppm. Follow-up assays returned up to 55.3 g/t Au, and some surface samples reached 2.87% Cu
Remember it’s still fundamentally a speculation on exploration
Despite the impressive assays, GoldHaven doesn’t have a producing mine or an established economic resource. The key question remains whether the mineralization can become large, continuous and economically mineable. High-grade individual samples/holes can be extremely misleading in early-stage exploration.
Therefore, things to be aware of… a fairly long list
- They’re pre revenue and burn cash as a junior mining company (modest however); and with six projects there’s many opportunities for capital and management attention to eat into capital (double edge sword). If we look at financing in 2026, a LIFE financing closed June 9: 23M units at $0.25 for C$5.75M. Flow-through money brought 2026 totals to about $2.75M. A further flow-through raise of up to $2.0M was announced in August.
- It’s a retail stock; no institutions own it and strategic entities only account for 4.5% (of which, one individual owns 3.14% AND that individual has sold shares 3 times so far in 2026). This is not a game changer, but worth to consider.
- There is no mineral resource estimate completed on their flagship and they are heavily reliant upon surface grab samples.
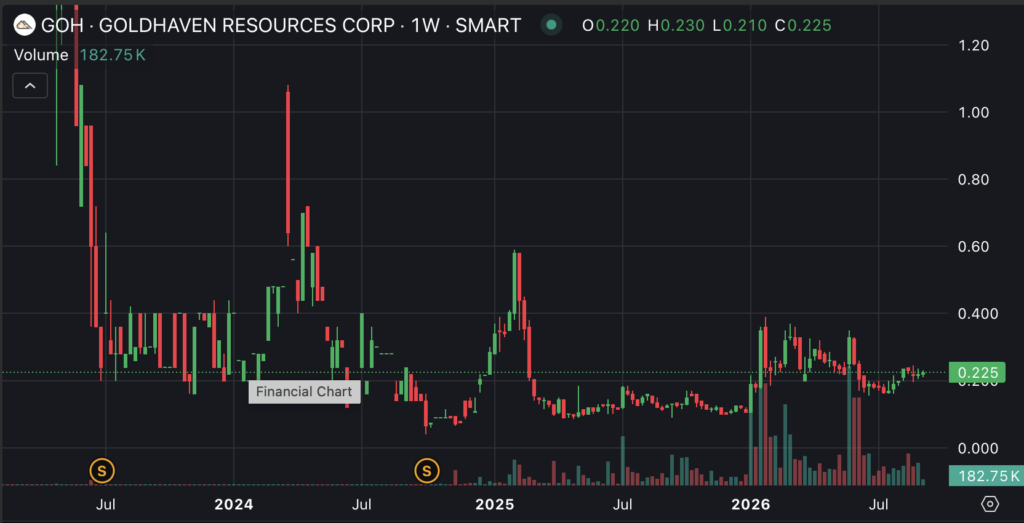
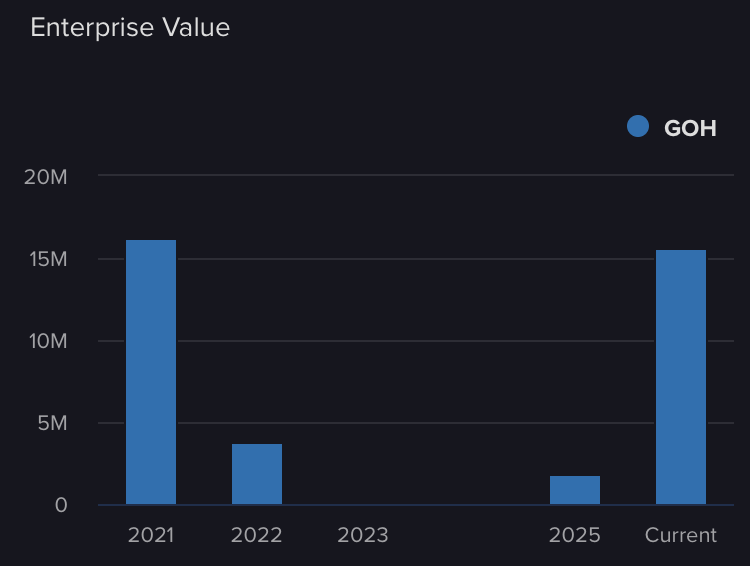
- The enterprise value hasn’t dramatically moved in the last 5 years
- When they paid for their assets (which again are their strong point), they did so by paying for them with future equity.
- History repeats; something else to be mindful of is the fact that they’ve had numerous projects with great geology before in Chile and after capital raises, they weren’t able to convert it into a growth story.
- Further to this, there were five CEOs in about five years. Across this time period there were 2 share consolidations. In June 2023 the shares were rolled back 1-for-6, leaving about 12.7M. Just about 15 months later they were rolled back again 1-for-4, leaving about 5.56M shares.
Recent News
–On October 22 the company reported several polymetallic sulphide zones at D Zone (Kuhn at Magno), up to 13 m long, with assays still pending (major item to watch)
–September they offered a non-brokered flow-through financing issuing 7,111,800 flow-through common shares (the “FT Shares”) at a price of $0.265 per FT Share for aggregate gross proceeds of $1,884,627.
–In response to additional investor demand, the Company has increased the size of the Flow-Through Offering to aggregate gross proceeds of up to $3.0 million (raised from $2.0 million).
Sampling at Magno returned indium values up to 334 ppm associated with sphalerite, the highest recorded concentration in the Cassiar District and a significant indicator of critical mineral potential.
Closing
Goldhaven Resources is a very risky bet from an execution standpoint. Moving through drill holes, CEOs and massive share counts have burned shareholders and put a serious question mark on their confidence/ability to execute at their flagship Magno. Furthermore, there are almost entirely retail investors involved which tells me the institutions are waiting for far more data to be proven and the team to stick with their plans before jumping in.
Goldhaven is one of the higher risk stocks I’ve written about–not because of it being a junior mining (this is already flaming with risk) but because they have a history of heavy dilution, recent failure, a name change, flipping through CEOs all while only holding reserve estimates and no official MRE completed. Management has shown time and time again to use your shareholder equity to keep the wheel turning.
With this said, surface samples have been incredibly mineral rich and positive. As we await their drilling assays to come through the next few months, this should let us know if there is a broader system they are sitting on that warrants further exploration and modeling for a re-rate.
So what are you buying with the Goldhaven Resources story?
You’re buying a significant amount of acreage with numerous targets that can be sold for cash or explored themselves, very promising assay results that prove there’s a real system here to get behind, and what interests me the most. Tungsten.
Tungsten is a strategic metal, and Western governments are working to reduce dependence on Chinese supply. The company has pointed to a recently announced US$450 million U.S. government investment to secure tungsten supply–not that Goldhaven would receive this, but there will be immense sums of capital come towards mineable Tungsten deposits.
For the time being, GoldHaven remains funded to live another year which will go into Magno and Copeçal, so shareholders shouldn’t expect any dilution in the next 3-6 months from when this is posted.
I would wait for the assays this year to come through to evaluate their mineral contents and grades. So much has to be investigated, funded and expanded, I don’t believe the assays alone will jump the share price away from you and be “too late” to buy. Furthermore, if they continue to receive great drill results with the gold and tungsten tailwinds and this were to appreciate the share price a great deal–I would exit the stock before massive dilutive forces come again.
