Company
Great Pacific Gold Corp. operates a portfolio of high-grade gold projects in Papua New Guinea (PNG) and Australia. In PNG, it holds a significant 2,513 sq. km mineral exploration land package. It includes early-stage and advanced-stage exploration targets with high-grade epithermal vein and porphyry-style mineralization present.
Its Arau Project consists of two exploration licenses, located in the Kainantu region, and includes the Mt. Victor Prospect, hosting copper and gold mineralization. Its Wild Dog Project consists of one granted exploration license, EL 2761, and one exploration license application, ELA 2516, located on the island of New Britain and about 50 km southwest of Rabaul and Kokopo, PNG. Its Kesar Creek Project consists of one exploration license, EL 2711, and is contiguous with the K92 Mining Inc. tenements. Its The Tinga Valley Property consists of one exploration license, EL2720, located in the Papua Mobile Belt, which is host to several Tier 1 copper and gold mines.
Clear 3 Investment Reasons
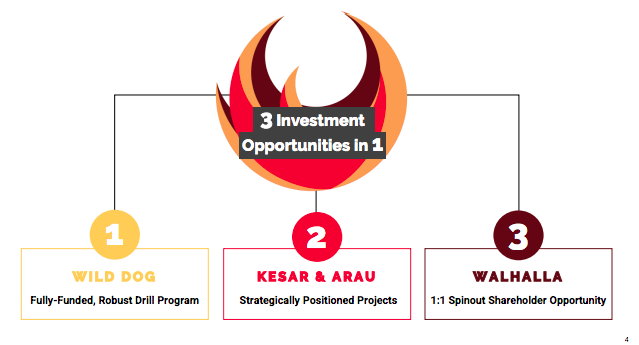
From their recent presentation (above)
Great Pacific Gold own their own project is promising, but also the 7% stake in Golden Cross (AUX.V).
Wild Dog
- Large scale, high grade
- Fully funded program
- Continuous news flow
They are currently completing diamond drilling here which has historic mining along the region and potential depths up to 1000m and beyond.
Kesar & Arau
- Strategic land holdings
- Contiguous with K92’s Kainantu Mine
- Walhalla (spin out)
- Immediate value at record rate
- 1:1 spinout – 2% NSR
- Historical high yield & grade
Numbers
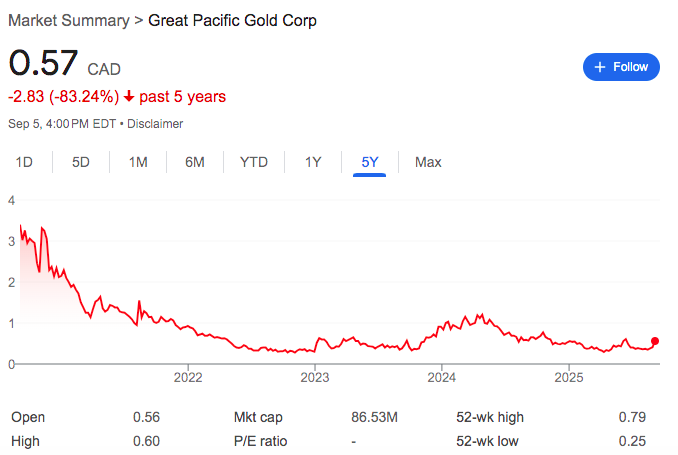
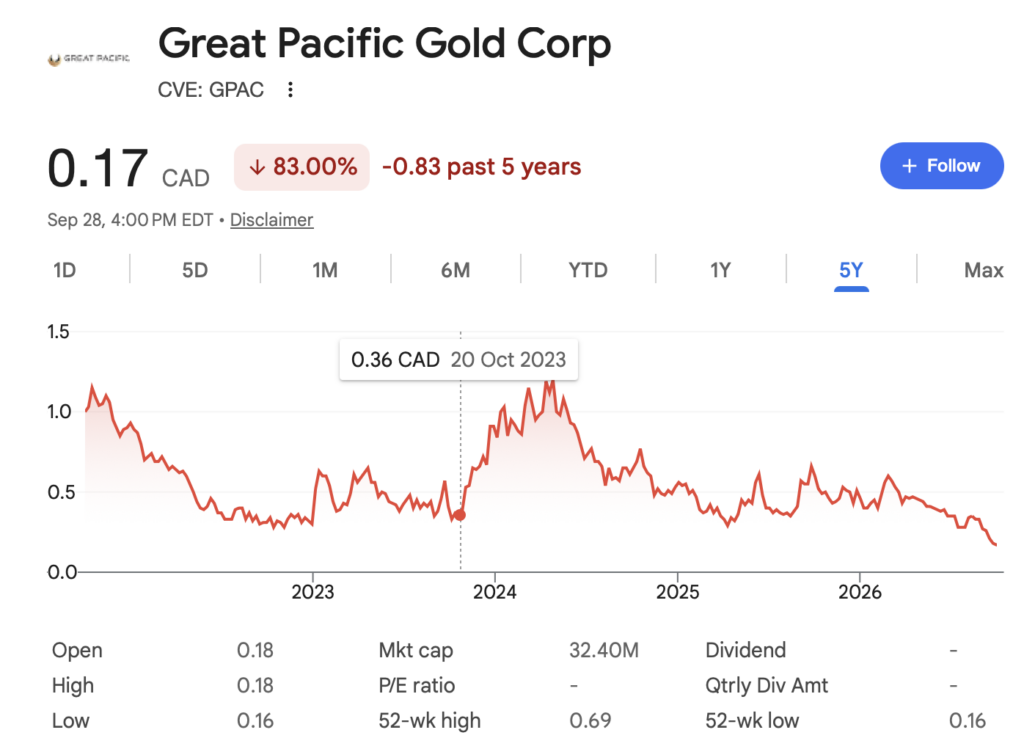
C$27.45M market cap
When I first noticed Great Pacific they had $18M cash in hand –> this cash amount is exploration budget of @K92Mining / $KNT.TO (A company that holds a $3.8B market cap also present nearby)… The latest figure is cash at C$5.68M at March 31, 2026, just before the C$20M raise closed.
Quarterly operating burn has run around C$2.4–4.2M
+ Golden Cross (AUX) shares paid GPAC 6,000,000 shares in 2025 for its Reedy Creek and Providence projects.
Beaten Up (more below)
Raises
Mid 2025:
Great Pacific Gold Corp. GPAC (OTCQX: FSXLF) V3H is pleased to announce that it has entered into an agreement with Canaccord Genuity Corp., as lead agent on behalf of a syndicate of agents, in connection with a best efforts private placement of up to 22,230,000 units of the Company at a price of $0.45 per Unit for aggregate gross proceeds of $10,003,500. They ended up at a closed upsized amount at C$16.9M on July 3, 2025.
In April 2026, the company closed a massive, upsized public offering of 42.6 million units at $0.47 per unit, raising over $20 million. While this brought in cash for their exploration projects, it flooded the market with new shares and attached warrants heavily diluted existing shareholders and dragged the share price down significantly below the offering price
Grades
Latest, key highlights from the program include surface sampling results of 0.8 meters at 127 grams per tonne gold equivalent (AuEq) from the Main Vein, and 2.4 meters at 22 g/t AuEq from additional Main Vein samples.
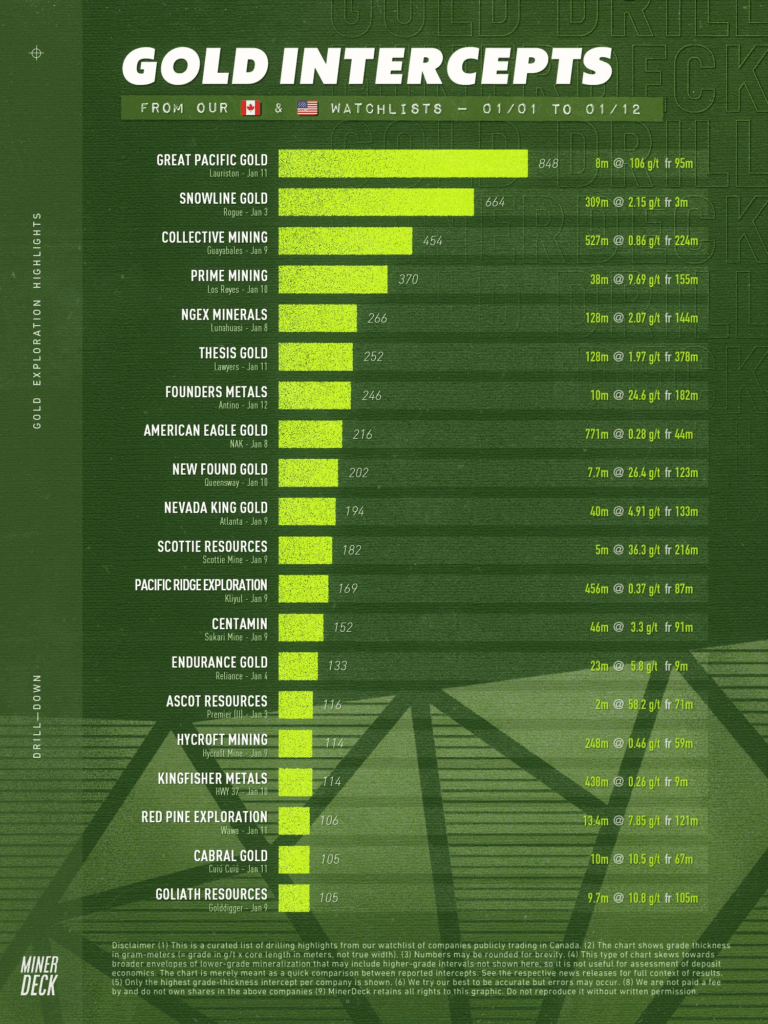
In drilling, Hole WDG-09 intercepted 5.0 meters at 4.91 g/t AuEq from 169 meters depth as of Sept 2025. Moving forward, we can expect more results as the company has completed ten drill holes to date and plans to continue the expanded 28-hole program into early 2026
8.4 meters at 50 g/t AuEq Drilled at Great Pacific Gold’s Wild Dog Project
9.5 metres @ 13.8 g/t AuEq Intercepted at Great Pacific Gold’s Wild Dog (12.61 g/t Au, 0.62% Cu, 14.63 g/t Ag)
Overall, Wild Dog is providing high-grade Au-Cu intercepts
Join the Soapbox Today for Free Speech writesoapbox.com
Why it fell down 80%
1. Kavasuki’s early holes didn’t hold up. The first holes were excellent and drove the initial rallies. Later holes were much weaker, such as 5.2m at 1.02 g/t in KVH-06 and 11.5m at 0.73 g/t in KVH-12 compared to the >2.5g/t results. In September the company concluded that the strongest mineralisation sits between surface and about 70m vertical depth, and the main vein continues below that but didn’t carry significant gold at the depths tested. Their story being told before this were gold findings up to 1000m.
2. The geophysics that pointed to targets was reinterpreted. The company now attributes the main historical IP response to disseminated pyrite in volcanic and siltstone units, not to gold. That weakens a key tool behind its claims about the whole district.
3. Kasie Ridge, the top target, was effectively a miss. In January the company called it its highest-priority target. The two-hole program found best gold values of 1.55 g/t in single samples in KAS-02, and a maximum of just 0.11 g/t in the 595.7m KAS-01A. The company did not confirm porphyry potential and says the interpreted magmatic source remains untested. The headline drill program say the findings “confirms large magmatic-hydrothermal system,” but the numbers don’t necessarily suggest a discovery.
4. A long stretch with no results. The November 4 update this year covered 16 holes, about 3,600m, at Magiabe and Mengmut, and stated that no new assay results were reported. All of those assays are still pending and will be released in complete batches for each target.
5. Dilution and other pressure. The April financing raised the share count to about 196 million shares. A senior executive also left: the VP Corporate Development resigned to join K92 Mining’s board, too.
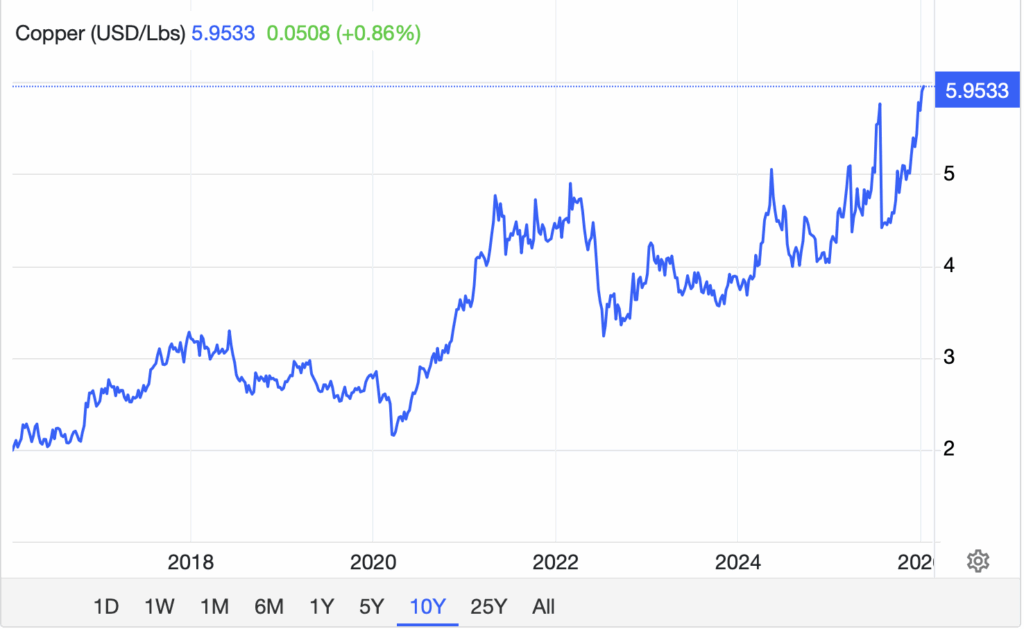
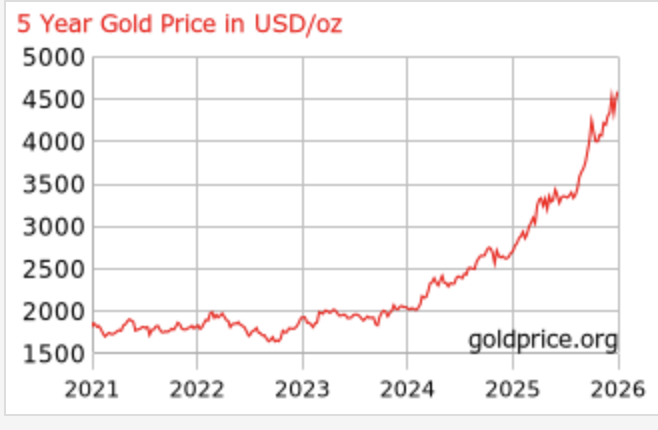
Underlying Metal Prices
Being in the dark makes this a speculation
- Lottery ticket type economics. If cash really is in the high teens to low C$20Ms against a C$27M market cap, the market values the whole 15km Wild Dog land package at under C$10M…peanuts. That isn’t a valuation of a business, it’s a cheap option. If they develop an economical deposit we’d be getting it for next to nothing right now.
- The next catalysts are already drilled. All Magiabe and Mengmut assays are pending, covering about 3,600m. Elamaraka is next, with 10-12 holes for about 2,400m planned. The result is binary and arrives within months: good assays could re-rate a stock this beaten down, and poor ones probably mean another leg lower. This alone makes it well into the speculation category.
- High grade has been shown to exist. Size remains unknown. This is what had first turned my head towards the company (and noting the majors in the area). Sinivit has returned 8.4 metres at 50 g/t AuEq from 154 metres. The bet is whether there are enough high-grade shoots to add up to a deposit. That’s an exploration question, which is exactly what speculation means.
- Expectations are low, so a decent result moves the stock more. After this year’s misses, the bar for a positive surprise is low. The usual Canadian tax-loss selling in November and December could also push the price below where the fundamentals sit until January. This is a fantastic situation for those who love eating higher risk for higher rewards…
Ownership
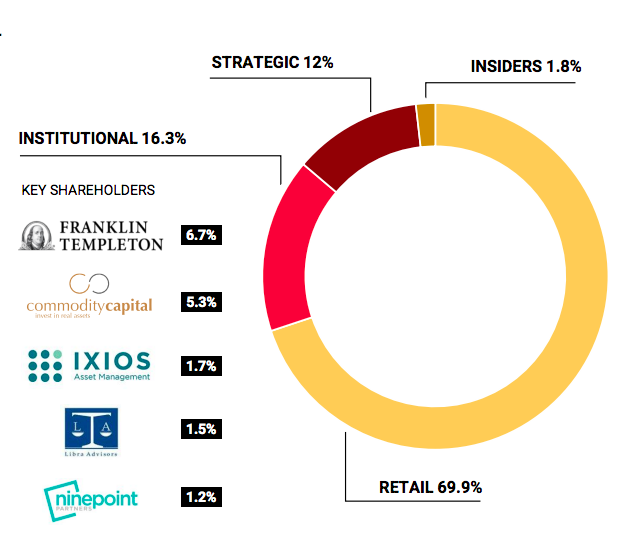
They do have some institutional ownership, which is nice to see, but its overwhelmingly retail based.
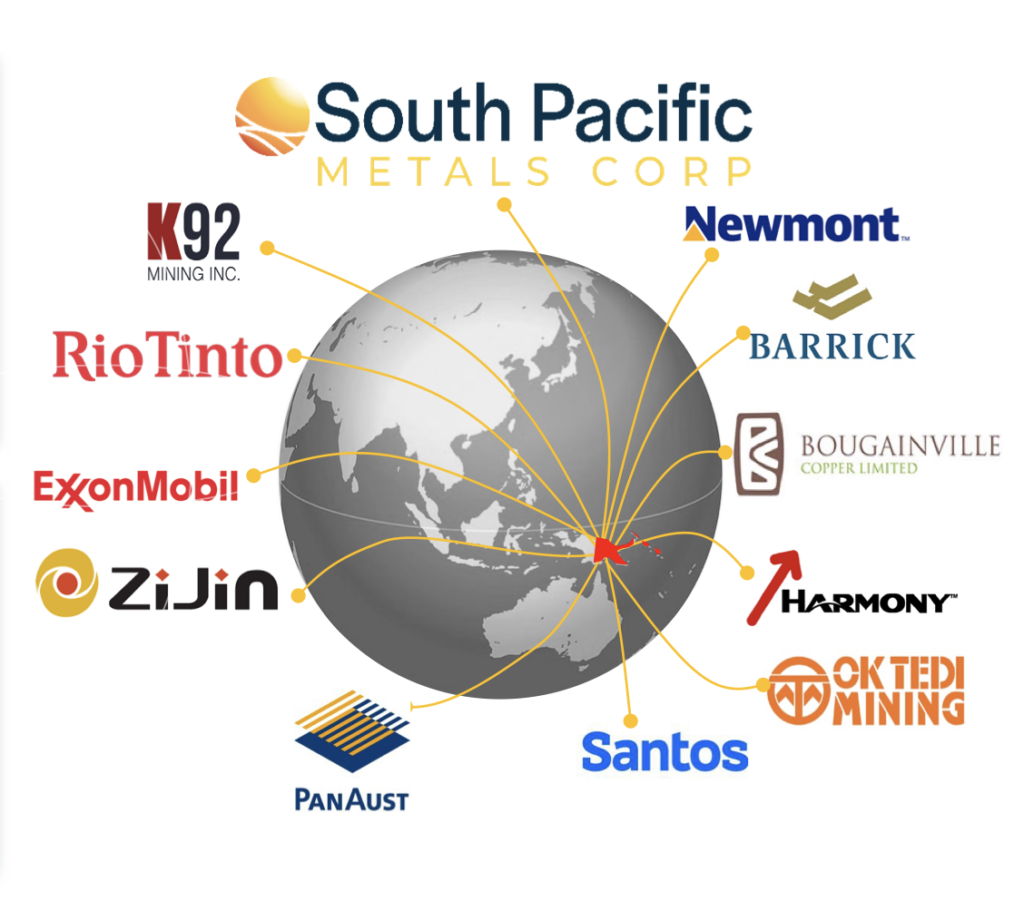
Let’s check how their neighbors are doing…
Spin Out News, Small Cash
…is pleased to announce that it has set November 27, 2025 as the date on which the special meeting of shareholders will occur to approve the spinout of Walhalla Gold Corp. (“Walhalla”), whereby Great Pacific distributed the shares of Walhalla to the shareholders of Great Pacific.
It completed in December 2025 and listed on the CSE in April. Your C$2.62M value assumed AUX at about C$0.73. AUX closed at C$0.165 in June 2026, which puts 3.6M shares at roughly C$0.6M…a modest amount.
Insurance covers risk, but not asset protection. Heads I win, Tails I lose, can be done using insurance…but it’s a terrible method if someone wants your entire coin. For more structuring, get in touch with me at contact@imontheball.com for a call or joining as a managed member.
Details to Be Excited About
At the moment they have a strong treasury. GPAC has maintained a highly robust balance sheet with cash reserves hovering near C$26.3 million, heavily buffered by a major $20M equity raising round. They do not need emergency capital. Moving forward it’s worth noting that drilling costs average about C$350 per meter, an efficient figure.
Details to be worried about
It’s not possible to officially measure a P/NAV ratio since there is no defined deposit just yet. A resource estimate with tonnes and grade, metallurgical recoveries and a mine plan is required but GPAC has:
- No resource estimate. During June to November 2026 there were no resource estimates.
- No recovery data. No metallurgical testing has been carried out on Wild Dog mineralized samples. The gold-equivalent figures even borrow recovery assumptions from K92 Mining’s Kainantu mine.
- No analyst coverage. Great Pacific Gold is covered by 0 analysts.
- Risking a 14-18% dilution if the stock rallies. The April 2026 warrants run for a two-year period, so they can still be exercised until around April 2028. If the stock gets back above 70 cents by then, they’ll be exercised. That would also bring in roughly C$15M, but add a considerable number of shares outstanding.
Warning of the jurisdiction from foreigner in PNG I’ve found on a forum
If there is one thing to take from my 20yrs working in emerging markets like PNG; that is DO NOT try to change the way they do business. Instead try to understand it, find “trustworthy” local partners, and take advantage of the inefficiencies by doing business their way, but better.
Business culture, social structures, hierarchies, political, economic, social business systems are all ingrained in a way that we cannot start to comprehend as outsiders
The fastest way to part the cash from your wallet, is to step into an inefficient, chaotic market structure and assume your western mind will improve it. Your hard money will be gone in no time.
Closing
PNG is a location that I imagine many investors tend to completely overlook or not care about in the least. The reasons for not doing any mainstream business are obvious given that the country can be regarded as entirely backward and even dangerous at times.
The risks are real and the share price has responded accordingly. Right now, they are largely priced into the shares as the market is expected further dilution, weak drill results and non-gold findings. From our point of view as investors, we don’t truly know what they’re possessing in the ground, but that’s where the opportunity lies.
Having said this, it’s difficult to argue that this is an investment we can feel confident about…instead we have to take a different approach: to speculate. Right now we do have good reasons to speculate they will uncover exciting results while their share price sits at 5 year lows.
We do know there’s some seriously high grade gold and copper deposits on this island and some of their drill results have alluded to this already. We also know that many of the big companies are now in the region singing the same song; gold and copper in PNG. Not only that, but for a low market cap explorer, it’s nice to see that they already have institutional ownership on their books. Finally, looking at the gold and copper price lately (and its upcoming supply issues), this screams an excellent speculative opportunity.
In the past I’ve wrote about the difference between investing and speculating and given the uncertainties that sit with GPAC, this is certainly in the latter category. However, with a high risk tolerance and a little bit of luck to unearth a gold bearing system–a re-rate in this crushed exploration company could be enormous. First step are the latest assay results.
